OGCI’s members drive emissions reductions
The data presented in this chapter reflects sustained individual action across OGCI member companies to reduce emissions, improve measurement and advance low-carbon solutions and technologies.
The examples below illustrate some of the operational improvements, technologies and investment that are helping drive progress across our members.
Through OGDC, we are sharing the experience, practices and technologies developed across our membership to help accelerate emissions reductions across the wider industry.
OGCI’s Reporting Framework and methodologies
Across our members
Selected actions, technologies and investments driving progress
SAF project assessment
Optimized turbine operations using methane measurement data
Methane detection drones
Storing CO2 in Xinjiang
Cooperating with NOCs on emissions reduction
Electrification and low-emissions design
Louisiana CCS expansion
Direct air capture development
Biodiesel shipping fuel trials and commercialization
Renewable diesel expansion
~92% OGMP Level 5 coverage4
13,000 methane sensors
total operated oil and gas production in 2025
of overall global oil and gas production in 2025
share of natural gas in operated portfolio in 2025
Production
In 2025, aggregate operated oil and natural gas production from OGCI’s 12 member companies was 3% higher year-on-year at 43.4 Mboe/day to meet growing global demand. Aggregate production from individual OGCI member companies represents 24% of global oil and gas from their operated assets in 2025.5
The overall increase in operated oil and gas production was driven by acquisitions and organic growth at five companies. This resulted in a decrease in operated production at three companies due to divestments.
Operated oil production overall increased 4% compared with the previous year, while operated gas production was unchanged at 14.4 Mboe/d. This resulted in natural gas representing a 33% share of the operated portfolio.
In 2025, OGCI members total oil and gas production on an equity basis, reported by 11 companies, was 37.2 Mboe/day, a 4% increase year-on-year. In 2025, OGCI member companies accounted for 20.7% of global oil and gas production on an equity basis.
| OGCI indicators | Units | 2017 | 2018 | 2019 | 2020 | 2021 | 2022 | 2023i | 2024i | 2025 | 2024-2025 | 2017-2025 |
| Operated oil and gas production | Mboe/day | 45.0 | 45.6 | 45.8 | 43.5 | 43.5 | 42.2 | 41.2 | 42.2 | 43.4 | 3% | -4% |
| Operated oil production | Mboe/day | 29.8 | 29.9 | 29.7 | 28.4 | 27.9 | 27.8 | 27.3 | 27.8 | 29.0 | 4% | -3% |
| Operated gas production | Mboe/day | 15.2 | 15.7 | 16.1 | 15.1 | 15.6 | 14.4 | 14.0 | 14.4 | 14.4 | 0% | -5% |
| Gas as a share of total operated production | % | 34% | 34% | 35% | 35% | 36% | 34% | 34% | 34% | 33% | -3% | -2% |
| Equity Oil and gas production | Mboe/day | 42.5 | 42.4 | 42.9 | 41.6 | 41.1 | 41.7 | 41.0 | 35.8
(11) |
37.2
(11) |
4% | -12% |
i. 2023 and 2024 data restated.
GHG emissions (operated)
In 2025, OGCI’s member companies achieved the group’s ambition to reduce upstream operated carbon intensity to be at or below 17.0 kg CO2e/boe by 2025.6 OGCI members’ aggregate upstream operated carbon intensity was 16.5 kg CO2e/boe, a 4% decrease compared to the previous year and 27% lower than in 2017.
This reflects continued individual efforts to reduce flaring and methane emissions, investments in energy efficiency and projects to reduce carbon emissions in exploration and production, and portfolio changes.
In 2025, OGCI members’ total operated Scope 1 GHG emissions from all sectors (including upstream and downstream) was 542 Mt CO2e. This represents a slight decrease compared with the previous year’s total of 545 Mt and a 23% decrease compared with the 2017 baseline.
According to the International Energy Agency, global oil and gas operations emitted 5.1 Gt CO2e of Scope 1 and 2 greenhouse gases in 2022. OGCI members’ total operated Scope 1 emissions in 2025 of 542 Mt CO2e are equivalent to around 11% of the IEA’s operational emissions benchmark.7
In 2025, OGCI members’ aggregate upstream operated Scope 1 GHG emissions were 260 Mt CO2e, a slight decrease compared with 261 Mt in 2024.
Continued improvement in operational performance, in particular enhanced flaring management and energy efficiency initiatives, helped to offset a potential emissions increase associated with the 3% increase in operated oil and gas production.
In 2025, OGCI member companies’ aggregate operated Scope 1 GHG emissions were 28% lower than the 2017 baseline.
OGCI members’ aggregate upstream operated Scope 2 GHG emissions, using a location-based approach, were 46 Mt, up 3% over the previous year, mainly attributable to electrification of assets and recent acquisitions.
Scope 2 GHG aggregate emissions individually reported by 11 companies, using a market-based approach, were 16 Mt, a 11% decrease year-on-year due to continued electrification and increased purchases of Energy Attribute Certificates, which is evidence that electricity has been generated by renewables.
The location-based approach reflects the average emissions intensity of the local power grid whereas the market-based approach reflects a company’s specific energy contracts.
OGCI members are individually focused on continued efforts to improve Scope 2 reporting based on the market-based approach.
In general, downstream has shown slower progress than upstream. This is because refining and petrochemical operations are more energy intensive and often have fewer readily available abatement opportunities, making further reductions more challenging.
upstream carbon intensity in 2025
upstream carbon intensity
2025 vs 2017
total operated Scope 1 GHG emissions in 2025
| OGCI indicators | Units | 2017 | 2018 | 2019 | 2020 | 2021 | 2022i | 2023i | 2024i | 2025 | 2024-2025 | 2017-2025 |
| Upstream operated carbon intensity (mixed approach for Scope 2)ii | kgCO2e/boe | 22.7 | 22.1 | 21.3 | 20.4 | 19.2 | 17.6 | 17.7 | 17.2 | 16.5 | -4% | -27% |
| Total operated GHG emissions (Scope 1)iii | MtCO2e | 709 | 687 | 684 | 633 | 621 | 575 | 559 | 545 | 542 | 0% | -23% |
| Upstream operated GHG emissions (Scope 1)iv | MtCO2e | 362 | 349 | 343 | 311 | 298 | 268 | 263 | 261 | 260 | -1% | -28% |
| Upstream operated GHG emissions (Scope 2 location based)v | MtCO2e | 41.4 | 43.5 | 43.7 | 39.4 | 38.2 | 37.9 (10) | 38.2 (10) | 44.4 | 45.8 | 3% | 10% |
| Upstream operated GHG emissions (Scope 2 market based) | MtCO2e | N/A | N/A | N/A | N/A | N/A | N/A | 14 (8) | 18 (11) | 16 (11) | -11% | N/A |
i. 2022 data restated for the upstream carbon intensity indicator only. 2023 and 2024 data restated across all KPIs in this table.
ii. This is the key performance indicator for OGCI’s upstream carbon intensity ambition. It includes upstream carbon dioxide and methane emissions, both Scope 1 and 2, on an operated basis. It excludes emissions from gas liquefaction and gas-to-liquids. This indicator has been calculated using a mixed methodology that combines market-based and location-based approaches for upstream Scope 2 emissions, with priority given to market-based data. In 2025, 11 companies reported upstream Scope 2 emissions using the market-based approach, and one company using a location-based approach. In last year’s report, companies unable to provide market-based upstream Scope 2 emissions data were excluded for the 2022, 2023 and 2024 datapoints. As 2025 is the target year for the collective upstream carbon intensity ambition, OGCI used a mixed methodology across all years to ensure full representation of all 12 member companies.
iii. Numbers are rounded. This figure includes direct (Scope 1) emissions of carbon dioxide, methane and nitrous oxide (for those companies that report it) from all operated activities (upstream as well as downstream, which includes refineries and petrochemicals). The methane emissions were converted to CO2 equivalent using different global warming potentials (GWP) depending on the company. In 2025, six companies reported with AR6; five companies with AR5 and one company with AR4.
iv. Upstream activities comprise all operations from exploration to production and gas processing (up to the first point of sale), including LNG liquefaction plants if located before the first point of sale.
v. Scope 2 emissions were not calculated in a homogenous way across companies from 2017-2021 as some used a location-based methodology and others used market-based.
upstream methane intensity in 2025
upstream methane emissions in 2025
upstream methane emissions
2025 vs 2017
Methane emissions
OGCI members reported an aggregate upstream operated methane intensity of 0.13%. This is the fifth year the group has successfully met its ambition to keep methane intensity well below 0.20%.
The 2% increase in methane intensity compared to the previous year’s result of 0.12% comes as two companies improved their methane quantification methodologies. At the same time, seven companies reduced their methane emissions.
Since 2017, OGCI members have decreased their aggregate upstream operated methane intensity by 58%.
Looking to 2030, OGCI CEOs said in a statement in March that the group will continue to report on emissions and strive to improve individual methane performance and measurement, and aim for 0.1% collectively.8
In 2025, upstream operated methane emissions totaled 0.76 Mt of methane. This represents a 1% decrease compared with 0.77 Mt in 2024, and a 61% decrease compared with 1.95 Mt in 2017.
The upstream sector accounted for around 92% of OGCI member companies’ total methane emissions in 2025. Venting, stationary combustion sources such as turbines, and flaring are the largest sources of upstream methane emissions.
OGCI member companies are working to reach near zero methane emissions from their operated assets by 2030.9 They are sharing what they are learning about detection, measurement and abatement across the industry.
| OGCI indicators | Units | 2017 | 2018 | 2019 | 2020 | 2021 | 2022 | 2023i | 2024i | 2025 | 2024-2025 | 2017-2025 |
| Upstream operated methane intensityii | % | 0.30 | 0.25 | 0.23 | 0.21 | 0.17 | 0.15 | 0.15 | 0.12 | 0.13 | 2% | -58% |
| Total operated methane emissionsiii | MtCH4 | 2.14 | 1.85 | 1.67 | 1.42 | 1.25 | 1.01 | 0.97 | 0.82 | 0.83 | 1% | -61% |
| Upstream operated methane emissions | MtCH4 | 1.95 | 1.69 | 1.56 | 1.34 | 1.16 | 0.95 | 0.87 | 0.77 | 0.76 | -1% | -61% |
i. 2023 and 2024 data restated. OGCI began publishing equity emissions data in 2023, starting with 2021 data.
ii. This is the key performance indicator for OGCI’s 2025 upstream methane ambition of well below 0.20%. It includes total upstream methane emissions from all operated gas and oil assets. Emissions intensity is calculated as a share of marketed gas.
iii. This figure includes relevant operated activities (upstream, refineries, petrochemicals, power generation, etc).
Flaring (operated)
OGCI member companies continued to reduce flaring volumes and related greenhouse gas emissions from flaring in 2025, helping to support their ambition to eliminate upstream routine flaring by 2030.10
In 2025, OGCI members flared in aggregate 9.2 billion cubic metres (bcm) of gas. This total is equivalent to around 6% of the 167 bcm flared globally in 2025,11 while OGCI represents about 24% of global operated oil gas production.12
OGCI members’ aggregate routine flaring decreased to 1.45 bcm, down 74% since 2018, demonstrating that significant reductions are achievable while maintaining energy production.
In 2025, OGCI’s aggregate routine gas flared volumes upstream decreased by 14% year-on-year with three companies reporting zero routine flaring.
OGCI members’ aggregated volumes of natural gas flared upstream were 14% lower year-on-year. The overall decrease was driven by operational performance improvements, eight companies reporting fewer turnarounds and startup activities in 2025 and portfolio changes.
This resulted in an aggregate 16% decrease year-on-year in upstream flaring intensity to 4.3 million cubic metres per million tonnes of oil equivalent. In 2025, upstream flaring intensity was –61% lower than in 2017.
In 2025, GHG aggregate emissions from upstream flaring were 9% lower year-on-year at 26 Mt CO2e and 59% lower than in 2017.
total aggregate gas flared upstream in 2025
total aggregate gas flared upstream
2025 vs 2017
total in aggregate routine flaring upstream
total aggregate routine flaring upstream
2025 vs 2017
| OGCI indicators | Units | 2017 | 2018 | 2019 | 2020 | 2021 | 2022 | 2023i | 2024i | 2025 | 2024-2025 | 2017-2025 |
| Upstream flaring intensityii | Mm3/Mtoe | 10.8 | 9.5 | 9.2 | 7.6 | 7.4 | 5.6 | 5.6 | 5.1 | 4.3 | -16% | -61% |
| Total gas flared – Upstream | Mm3/Mtoe | 24,221 | 21,465 | 20,998 | 16,490 | 15,998 | 11,749 | 11,531 | 10,648 | 9,195 | -14% | -62% |
| Total routine gas flared – Upstream | Mm3/Mtoe | N/A | 5,636 (10) | 4,871 (10) | 4,250 (11) | 4,165 | 2,187 (11) | 1,892 (11) | 1,682 | 1,454 | -14% | -74% (v 2018) |
| Flaring GHG emissions – Upstream | MtCO2e | 62 | 57 | 55 | 44 | 42 | 30 | 29 | 28 | 26 | -9% | -59% |
i. 2023 and 2024 data restated.
ii. Upstream flaring intensity is calculated on the basis of the volume of gas flared per million tonnes of oil equivalent produced on an operated basis.
10 companies
Scope 1 equity GHG emissions in 2025
(10 companies)
Scope 2 equity GHG emissions in 2025
10 companies
Total equity methane emissions in 2025
GHG emissions (equity)
This is the fifth year of OGCI published data on equity emissions in line with OGCI’s ambition of greater transparency in aggregate emissions reporting.
Equity reporting includes emissions from assets where company participants hold equity share even where they are operated by partners.
In 2025, total GHG emissions on an equity basis for Scope 1 and Scope 2 (as reported by 10 companies) were overall 425 Mt CO2e and 46 Mt CO2e respectively. This compares with 562 Mt and 69 Mt for Scope 1 and Scope 2 respectively in 2021, the first year of published data.
Total methane emissions on an equity basis were 0.53 (10 companies) Mt of methane in 2025, up 3% from the previous year’s total of 0.52 Mt (nine companies) and 53% lower than 1.13 Mt published data from 2021.
| OGCI indicators | Units | 2017 | 2018 | 2019 | 2020 | 2021 | 2022 | 2023i | 2024i | 2025 | 2024-2025 | 2021-2025 |
| Total equity GHG emissions (Scope 1) | MtCO2e | N/A | N/A | N/A | N/A | 562 (10) | 596 (11) | 577 (11) | 431 (10) | 425 (10) | -1% | -29% |
| Total equity GHG emissions (Scope 2) | MtCO2e | N/A | N/A | N/A | N/A | 69 (10) | 83 (11) | 86 (11) | 46 (10) | 46 (10) | 1% | -33% |
| Total equity methane emissions | MtCH4 | N/A | N/A | N/A | N/A | 1.13 (10) | 0.95 (9) | 0.97 (10) | 0.52 (9) | 0.53 (10) | 3% | -53% |
| Equity methane emissions – upstream | MtCH4 | N/A | N/A | N/A | N/A | 1.09 (10) | 0.91 (11) | 0.90 (11) | 0.46 (10) | 0.45 (10) | -2% | -59% |
i. 2023 and 2024 data restated. OGCI began publishing equity emissions data in 2023, starting with 2021 data.
Low-carbon investment
In 2025, OGCI member companies’ aggregate low-carbon investment, including acquisitions, and research and development (R&D) totalled $28 billion, a decrease of 10% compared to the previous year.
Overall acquisitions increased 22% year-on-year and investment in low-carbon projects decreased by 16%.
While some companies reduced spending on renewable energy projects, investment in carbon capture, utilization and storage (CCUS) and direct air capture (DAC) projects increased around a third as some companies concentrated on the technology as part of their respective strategies to reduce emissions from hard-to-abate sectors.
In 2025, overall R&D spending on low-carbon technologies remained steady at $2.3 billion and comprised 41% of total R&D spend.
Since 2017, OGCI member companies’ cumulative investment in low-carbon technologies and projects, including investment, R&D and acquisitions, amounted to $156 billion.
total low-carbon investment in 2025
cumulative low-carbon investment since 2017
R&D spend
in 2025
| OGCI indicators | Units | 2017 | 2018 | 2019 | 2020 | 2021 | 2022 | 2023i | 2024i | 2025 | 2024-2025 | 2017-2025 |
| Total invested in low-carbon projectsii | $ billion | 4.4 | 4.5 | 4.5 | 5.1 | 5.6 | 9.7
(11) |
21.5
(11) |
24.3 | 20.3 | -16% | 357% |
| Total invested in low-carbon acquisitions | $ billion | 0.3
(5) |
1.0
(5) |
1.1
(9) |
1.6
(9) |
7.7
(9) |
13.2
(10) |
7.8
(10) |
4.4
(9) |
5.4
(8) |
22% | 1694% |
| R&D expenditures on low-carbon technologiesiii | $ billion | 0.7
(9) |
1.0
(9) |
1.0
(9) |
0.8
(11) |
1.3
(11) |
1.6
(11) |
2.0
(11) |
2.3
(11) |
2.3
(10) |
-1% | 231% |
| Share of R&D spent in low-carbon | % | 14
(9) |
15
(9) |
15
(9) |
12
(11) |
17
(11) |
30
(11) |
35
(11) |
39
(11) |
41
(10) |
5% | 192% |
i. 2023 and 2024 data restated
ii. Low-carbon energy technologies include but are not limited to wind, solar and other renewable energies, carbon-efficient energy management, CCUS, blue and green hydrogen, biofuels, synfuels, energy storage and sustainable mobility.
iii. R&D spending is additional to investment.
Mboe/day: Million barrels of oil equivalent per day
KgCO2e/boe: Kilograms of carbon dioxide equivalent per barrel of oil equivalent
Mt CO2e: Million tonnes of carbon dioxide equivalent
Mt CH4: Million tonnes of methane
Mm3: Million standard cubic metres
Bcm: Billion cubic metres
OGCI data consolidation and EY review process
All OGCI member companies already ensure that data reported to OGCI are independently verified.
Since 2016, OGCI has been working EY as an independent third party verifier.
EY performs a limited assurance, which includes an assessment of third-party verification conducted at company level on member-company data through the collection of supporting evidence and interviews with the external third parties of member companies.
EY’s statement this year covers 11 of OGCI’s 12 members.
Independent verifier’s report on a selection of indicators for the year ended December 31, 2025
We have been engaged by OGCI Limited, to perform a “limited assurance engagement”, as defined by International Standards on Assurance Engagements, hereafter referred to as the engagement, to report on a selection of OGCI indicators (the “OGCI Indicators”) detailed in Appendix 1 contained in OGCI’s performance data for the year ended December 31, 2025.
Basis for Qualified Conclusion
We had access to the nature and extent of third-party verifications conducted at company level on member-company data for only 11 companies13 out of the 12 OGCI’s member companies (representing more than 75% of the “Operated greenhouse gas emissions – all sectors (Scope 1)”; see Appendix 1 for other OGCI Indicators). Furthermore, the remaining company did not provide any data for 2025. OGCI has estimated that company’s data for 2025 using 2022 data as a reference.
Qualified Conclusion
Based on our work, described in the Nature and scope of the work section of this report, except for the possible effects of the matters described in the Basis for Qualified Conclusion section, nothing has come to our attention that causes us to believe that the OGCI Indicators are not presented, in all material respects, in accordance with the OGCI Reporting Framework dated July 2026.
Emphasis of matter
We draw attention to the OGCI Reporting Framework (Section 8: Detailed description of OGCI indicators) and to the OGCI Progress report which describe that:
- For the reporting of GHG emissions, companies can use the same methodology approach used for their public reporting of GHG emissions in other relevant documentation (e.g. Annual Report, Sustainability Report, etc.).
- Company and/or regulatory recording and reporting requirements for methane vary between and within OGCI companies and operating jurisdictions.
Our conclusion is not qualified in respect of this matter.
Understanding how OGCI has prepared the OGCI Indicators
The absence of a commonly used, generally accepted reporting framework or a significant body of established practice on which to draw, evaluate and measure sustainability information allows for different, but acceptable, measurement techniques that can affect comparability between entities and over time. Consequently, the OGCI Indicators need to be read and understood together with the OGCI Reporting Framework dated July 2026, which OGCI has used to prepare the OGCI Indicators.
Responsibility of OGCI
As part of this voluntary approach, it is the responsibility of OGCI to:
- disclose the OGCI Reporting Framework dated July 2026, available on OGCI’s website;
- consolidate member companies’ data and ensure their consistency;
- publish the consolidated OGCI Indicators on OGCI’s website.
Responsibility of OGCI’s member companies
As part of this voluntary approach, it is the responsibility of OGCI’s member companies to report to OGCI their data according to the OGCI Reporting Framework dated July 2026, to arrange external verification in accordance with OGCI’s and EY’s criteria, and to provide EY with a summary of the nature and details of the verification performed on their data at member-company level, together with associated findings.
Independence and quality management
We have maintained our independence and confirm that we have met the requirements of the Code of Ethics for Professional Accountants issued by the International Ethics Standards Board for Accountants, and have the required competencies and experience to conduct this assurance engagement.
EY also applies International Standard on Quality Management 1, Quality Management for Firms that Perform Audits or Reviews of Financial Statements, or Other Assurance or Related Services Engagements, which requires that we design, implement and operate a system of quality management including policies or procedures regarding compliance with ethical requirements, professional standards and applicable legal and regulatory requirements.
Responsibility of the independent verifier
Our responsibility is to express a conclusion on the presentation of the OGCI Indicators based on the evidence we have obtained.
We conducted our engagement in accordance with International Standard on Assurance Engagements 3000 Revised, Assurance Engagements Other Than Audits or Reviews of Historical Financial Information (”ISAE 3000 (Revised)”) and with professional standards applicable in France. Those standards require that we plan and perform our engagement to express a conclusion on whether we are aware of any material modifications that need to be made to the OGCI Indicators in order for them to be in accordance with the OGCI Reporting Framework dated July 2026, and to issue a report. The nature, timing and extent of the procedures selected depend on our judgment, including an assessment of the risk of material misstatement, whether due to fraud or error.
We believe that the evidence obtained is sufficient and appropriate to provide a basis for our limited assurance conclusions.
It is not our responsibility to give an opinion on the entire annual report or on the compliance of the OGCI Indicators with applicable legal provisions.
Nature and scope of the work
Procedures performed in a limited assurance engagement vary in nature and timing and are less in extent than for a reasonable assurance engagement. Consequently, the level of assurance obtained in a limited assurance engagement is substantially lower than the assurance that would have been obtained had a reasonable assurance engagement been performed. Our procedures were designed to obtain a limited level of assurance on which to base our conclusion and do not provide all the evidence that would be required to provide a reasonable level of assurance.
We conducted the work described below:
- We assessed the suitability of the OGCI Reporting Framework dated July 2026 in terms of its relevance comprehensiveness, reliability, neutrality and understandability by taking into consideration the best practices of the oil and gas industry.
- We conducted the following work related to the consistency and the arithmetical accuracy of member companies’ data reported by 11 OGCI’s member companies with the OGCI Reporting Framework dated July 2026:
- assessment of the appropriate application of the OGCI Reporting Framework dated July 2026 to the member-company data;
- analysis and investigation of member-company data value change in 2025 compared to 2024;
- calculation of consistency ratios and investigation to identify potential outliers among member-company data.
- We conducted a reconciliation between member-company data and publicly available information.
- We assessed the nature and extent of third-party verification conducted at company level on member company data against the following topics (hereafter the “Criteria”) through the collection of supporting evidence and interviews with the external third parties of member companies, based on the following:
- level of assurance;
- work program;
- assurance standard;
- audit findings;
- Scope 1 operated emissions coverage reached with site-level verifications;
- physical site visits;
- remote site visits;
- total man days allocated to the verification;
- third-party team members’ competencies.
- We conducted interviews with 11 OGCI’s member companies.
- We reviewed the consolidation performed by OGCI on the anonymized member-company data.
Our process for data consolidation and review
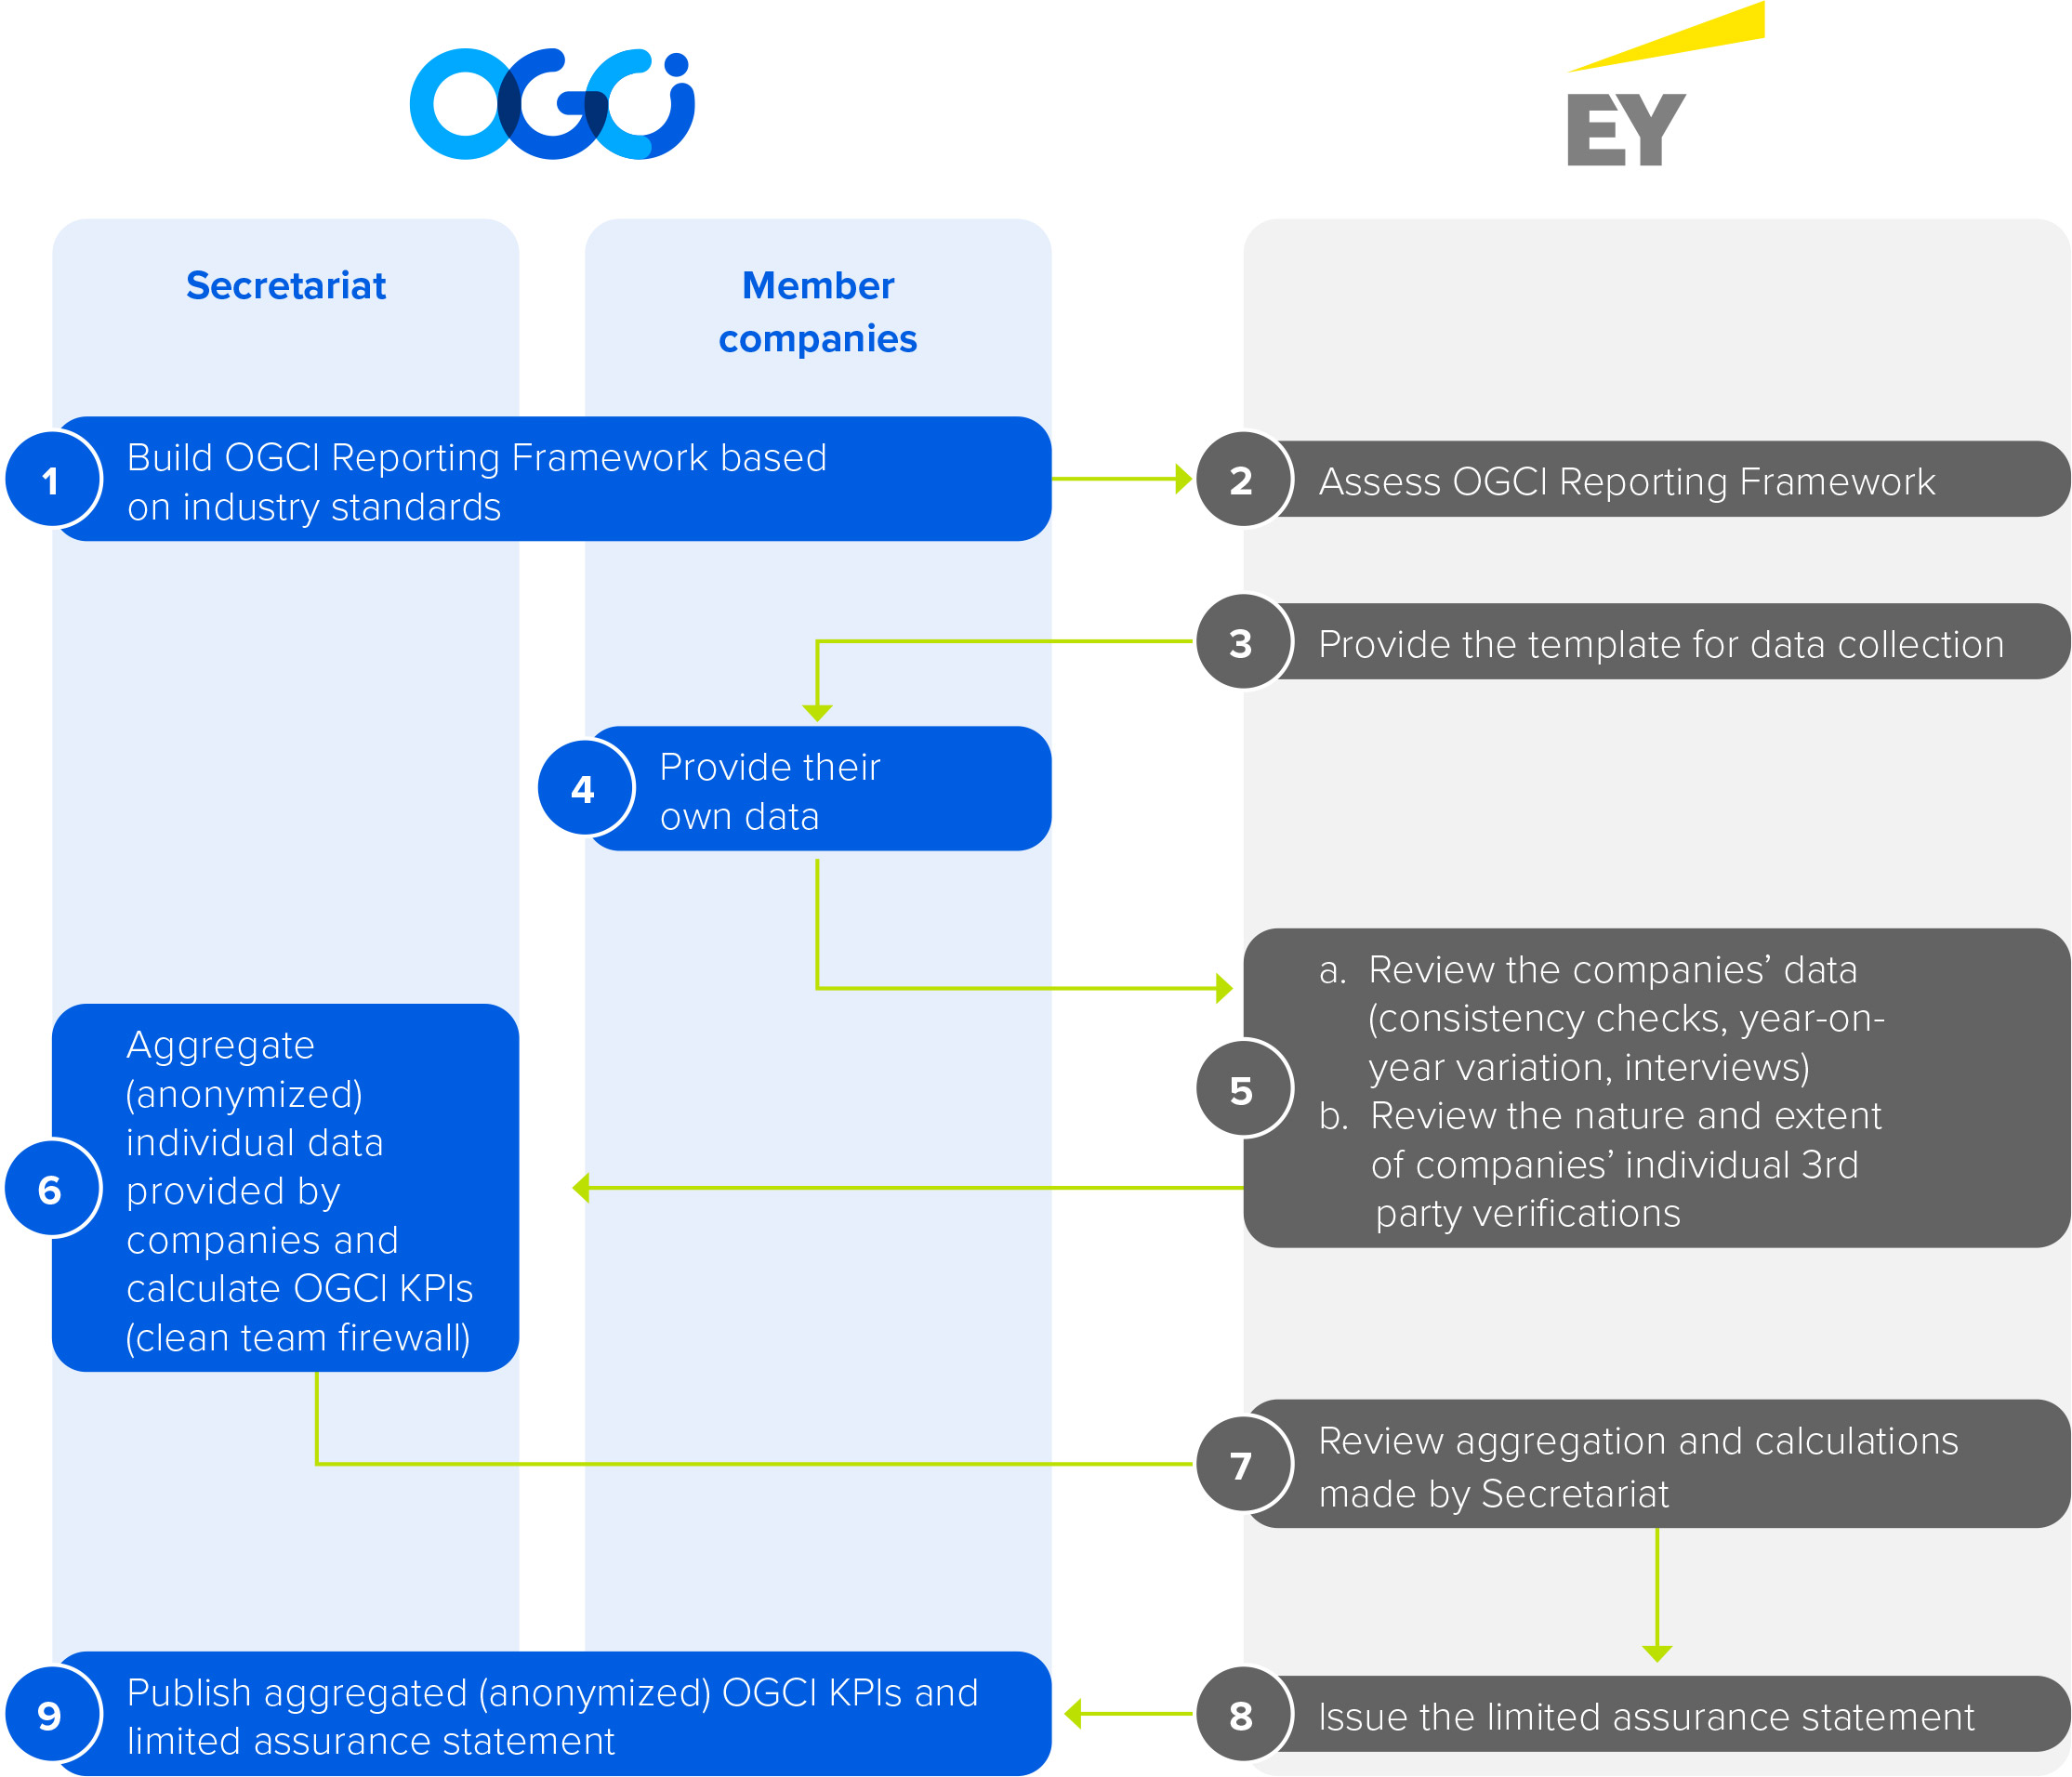
We consider that the work we have performed by exercising our professional judgment allows us to express a limited assurance conclusion; an assurance of a higher level would have required more extensive verification work.
Paris-La Défense, October 5, 2026
EY & Associés
Partner, Sustainable Development
Christophe Schmeitzky
Percentage of OGCI Indicators for which the third-party verification work has been shared with EY
| OGCI Indicators | OGCI Indicators value in the 2025 annual report (including 12 companies, unless otherwise stated)i | Percentage of the total 2025 OGCI indicators for 12 companies for which the third-party verification work has been shared with EY (coverage is presented based on 10 companies to preserve confidentiality) | |
| Operated greenhouse gas emissions – all sectors (Scope 1)v | 542 MtCO2e | > 75% | |
| Operated greenhouse gas emissions – upstream (Scope 1)v | 260 MtCO2e | > 81% | |
| Operated greenhouse gas emissions – upstream (Scope 2 Market-based) for 11 companiesii | 16 MtCO2e | > 99% | |
| Operated greenhouse gas emissions – upstream (Scope 2 location-based) | 46 MtCO2e | > 53% | |
| Operated methane emissions – all sectorsiii | |||
| 0.8 MtCO2e | > 61% | |
| > 36% | ||
| Operated methane emissions – upstreamiv | |||
| 0.8 MtCO2e | > 60% | |
| > 41% | ||
| Natural gas flared – upstreamiv | 9,195 MSm3 | > 92% | |
| Flaring greenhouse gas emissions – upstreamv | 26 MtCO2e | > 93% |
Notes:
i. OGCI Indicators include twelve companies, unless otherwise stated. As noted in the Basis for Qualified Conclusion, the reported OGCI indicators include estimated data for one company out of the twelve due to the absence of 2025 data provided by that company.
ii. “Operated greenhouse gas emissions – upstream (Scope 2 Market-based)” are reported exclusively using the market-based approach. As a result, the aggregated data includes only 11 out of 12 companies, since the remaining one report solely using the location-based method.
iii. “Operated methane emissions” indicator is considered covered by third-party verification if “Operated methane emissions – upstream” are covered, as methane emissions mainly occur in upstream activities. “Operated methane emissions – all sectors” and “Operated methane emissions – upstream” are not automatically considered as covered by third-party verification if only the “Greenhouse gas emissions – all sectors” are covered (as methane emissions generally represent a minor fraction of total greenhouse gas emissions).
iv. All indicators are operated. “Operated greenhouse gas emissions – upstream (Scope 1)”, “Operated greenhouse gas emissions – upstream (Scope 2 Market-based)”, “Operated greenhouse gas emissions – upstream (Scope 2 Location-based)”, “Natural gas flared – upstream” and “Flaring greenhouse gas emissions – upstream” indicators are considered covered by third-party verification if the “Greenhouse gas emissions – all sectors” are covered, as they are parts of the overall greenhouse gas emissions verification.
- As part of this engagement, EY reviews the third-party verification performed on member company data and assesses its alignment with OGCI reporting requirements.
One member company has been unable to submit audited performance data in time for the publication of the 2026 Progress Report. As a result, proxy data has been
used for the affected reporting years (2023, 2024 and 2025). For 2025 reporting, 2024 data was used as a direct proxy. For 2023 reporting, 2022 data was used
as a direct proxy. For 2024, available reported data was used where provided, while values for the following KPIs were estimated using 2022 performance data as a
proxy: total operated GHG emissions Scope 1 upstream, total operated GHG emissions Scope 2 upstream, operated methane emissions upstream, natural gas flared
upstream, routine gas flared upstream, flaring GHG emissions upstream and upstream flaring intensity. - See OGCI Reporting Framework.
- Figures and percentages are based on anonymized and aggregated information.
- Operated upstream assets, awaiting UNEP validation.
- Provisional estimate of global oil and gas production of approximately 180 Mboe/day in 2025, based on IEA indicators for oil production of 106.2 Mboe/day and global natural gas production of 73.8 Mboe/day. OGCI member companies’ share of total oil and gas production is 24.1% on an operated basis and 20.7% on an equity basis. Source: IEA Oil Market Report (January 2026), IEA Gas Market Report Q2 2026.
- This is the key performance indicator for OGCI’s upstream carbon intensity ambition. It includes upstream carbon dioxide and methane emissions, both Scope 1 and 2, on an operated basis. It excludes emissions from gas liquefaction and gas-to-liquids. This indicator has been calculated using a mixed methodology that combines market-based and location-based approaches for upstream Scope 2 emissions, with priority given to market-based data. In 2025, 11 companies reported upstream Scope 2 emissions using the market-based approach, and one company using a location-based approach. In last year’s report, companies unable to provide market-based upstream Scope 2 emissions data were excluded for the 2022, 2023 and 2024 datapoints. As 2025 is the target year for the collective upstream carbon intensity ambition, OGCI used a mixed methodology across all years to ensure full representation of all 12 member companies.
- IEA (2023), Emissions from Oil and Gas Operations in Net Zero Transitions. The IEA estimates that the production, transport and processing of oil and gas resulted in 5.1 Gt CO2e of Scope 1 and 2 greenhouse gas emissions globally in 2022. OGCI comparison calculated by dividing OGCI members’ total operated Scope 1 emissions in 2025 (542 Mt CO2e) by the IEA global operational emissions benchmark (5.1 Gt CO2e).
- See OGCI CEO Statement, March 2026.
- OGCI defines near zero upstream methane emissions as well below 0.20% methane intensity.
- Global gas flared globally in 2025 was 167 bcm, according to the World Bank Global Gas Flaring Tracker published in 2026.
- In 2025, OGCI member companies’ aggregated operated oil and gas production was 43.4 Mboe/day, OGCI Performance Data. OGCI member companies’ share of total oil and gas production in 2025 was is 24.1% on an operated basis and 20.7% on an equity basis. Source: IEA Oil Market Report (January 2026), IEA Gas Market Report Q2 2026.
- Per World Bank Zero Routine Flaring by 2030 initiative.
- The coverage percentage for “Operated greenhouse gas emissions – all sectors (Scope 1)”, along with other coverage percentages listed in Appendix 1, is presented based on a scope of 10 companies, in order to preserve confidentiality.